
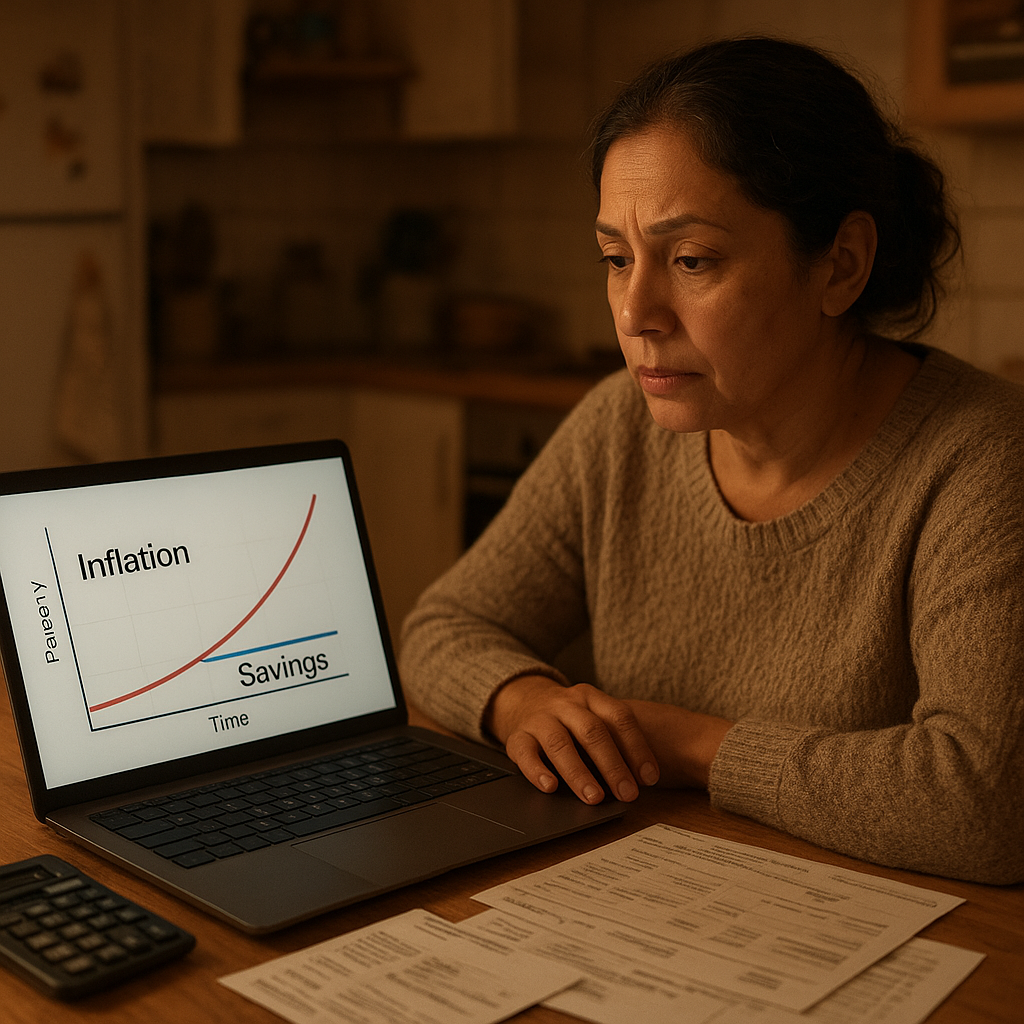
You’ve been diligently setting money aside every month. Your savings account balance is growing, and on paper, everything looks fine. But here’s the uncomfortable truth: even when your savings are increasing in number, they may be shrinking in value. This is the quiet, persistent work of inflation — and most people don’t notice it until the damage has already been done.
Inflation isn’t dramatic. It doesn’t announce itself the way a stock market crash does. Instead, it chips away at your purchasing power gradually, year after year, until the £10,000 you carefully saved feels more like £8,000 or £7,000 in real-world terms. Understanding how this process works — and what you can do about it — is one of the most important things any saver or investor can learn.
What Is Inflation, and Why Does It Matter for Savers?
At its core, inflation refers to the general rise in the price of goods and services over time. When inflation is running at 4% annually, something that cost £100 last year now costs £104. That might not sound alarming in isolation, but compound that effect over a decade, and the numbers become far more significant.
In the UK, inflation is most commonly measured using the Consumer Prices Index (CPI), which tracks price changes across a basket of everyday goods and services — from food and clothing to transport and energy. The Bank of England targets a 2% inflation rate as ideal for a healthy economy, but in recent years, inflation has frequently exceeded that target, sometimes dramatically so.
Between 2022 and 2023, UK inflation reached highs not seen in over 40 years, briefly surpassing 11% as measured by the Consumer Prices Index including owner occupiers’ housing costs (CPIH). During that period, savers who kept money in standard easy-access accounts earning 1–2% interest were effectively losing purchasing power at a rate of nearly 9–10% per year.
The Difference Between Nominal and Real Returns
This brings us to one of the most important concepts in personal finance: the distinction between nominal returns and real returns.
Your nominal return is the straightforward interest rate your savings account advertises — say, 3.5% annually. Your real return, however, accounts for inflation. If inflation is running at 4%, your real return is actually -0.5%. You’re technically earning interest, but you’re losing ground in terms of what that money can actually buy.
The formula is simple enough:
Real Return ≈ Nominal Interest Rate − Inflation Rate
So if your ISA pays 2% and inflation sits at 3.5%, your real return is approximately -1.5%. Every year, your savings quietly lose a fraction of their true value — not because you’ve spent anything, but simply because time has passed.
How Inflation Affects Different Types of Savings
Not all savings are affected by inflation in the same way. Where you keep your money matters enormously when inflation starts to bite.
Cash Savings Accounts
Standard cash savings accounts — whether easy-access, notice accounts, or fixed-rate bonds — are the most directly vulnerable to inflation. The interest rates on these accounts are fixed or change slowly, whereas inflation can accelerate quickly in response to economic events. During periods of high inflation, cash savers often find themselves in the frustrating position of watching their purchasing power erode despite dutifully adding to their pot.
That said, fixed-rate bonds and cash ISAs with competitive rates can partially offset inflation, particularly during periods of higher interest rates. During 2023, some UK fixed-rate bonds were offering rates above 5%, which, as inflation began to fall back towards 4%, started to look more attractive in real terms.
Instant-Access and Current Accounts
Money sitting in a current account or a poorly paying instant-access account is arguably the most exposed to inflation’s effects. Many current accounts still pay minimal interest — sometimes as little as 0.01%. At any level of meaningful inflation, this represents a significant real-terms loss over time.
Long-Term Savings and Pension Pots
For those saving over decades — particularly in pension schemes — inflation is a major consideration. A pension pot that seems substantial today may provide a much lower standard of living in retirement than anticipated, simply because the purchasing power of that money has been steadily whittled down.
Many defined contribution pension schemes aim to invest in assets that grow faster than inflation over the long term, but this isn’t guaranteed. Understanding the real value of your projected retirement income — adjusted for likely inflation — is an essential part of retirement planning.
The 5 Key Effects of Inflation on Your Financial Life
When people ask about the effects of inflation, they’re often thinking about rising prices at the supermarket. But the impacts run much deeper than that:
- Reduced purchasing power: The most direct effect — your money buys less. This is felt most acutely by those on fixed incomes or with large cash savings.
- Lower real investment returns: Even investments that grow in nominal terms may deliver disappointing real returns once inflation is factored in.
- Increased cost of borrowing: Central banks typically raise interest rates to combat inflation, which pushes up mortgage rates, loan costs, and credit card interest. understanding how credit works becomes especially important during these periods.
- Wealth redistribution: Inflation tends to benefit borrowers (whose debts shrink in real terms) and penalise savers and creditors (whose assets lose real value).
- Uncertainty in financial planning: High or unpredictable inflation makes it harder to plan for the future, from retirement to saving for a house deposit.
Does Inflation Have Any Positive Effects?
It’s worth acknowledging that not all inflation is catastrophic — in fact, moderate, predictable inflation is generally considered healthy for an economy. Here’s why:
- It encourages spending and investment: When people expect prices to rise, they’re more motivated to spend or invest now rather than hold cash indefinitely.
- It reduces the real burden of debt: If you have a fixed-rate mortgage, inflation effectively reduces the real value of what you owe over time.
- It gives central banks room to manoeuvre: A small buffer of inflation allows interest rates to be cut in a recession without hitting the so-called “zero lower bound.”
The problems arise when inflation becomes high, sustained, or unpredictable — as it did in many countries during 2022 and 2023. At that point, the negative effects for ordinary savers and consumers far outweigh any macroeconomic benefits.
How Can You Counteract the Impact of Inflation on Your Savings?
The good news is that there are concrete, practical strategies for protecting your savings against inflation. None of them are magic bullets, but used together, they can significantly reduce the real-terms damage inflation causes.
1. Seek Out High-Interest Savings Accounts
It sounds obvious, but many people leave money in low-paying accounts simply out of inertia. Regularly reviewing and switching to the best-available savings rates — including cash ISAs, fixed-rate bonds, and high-interest current accounts — can meaningfully close the gap between your savings rate and inflation.
Comparison sites and the Bank of England’s own published data on savings rates can help identify competitive products. Even a difference of 1–2% in interest rate translates to a significant sum over several years on a large deposit.
2. Consider Inflation-Linked Investments
Some financial products are specifically designed to keep pace with inflation. UK government index-linked gilts, for instance, adjust both the principal and interest payments in line with the Retail Prices Index (RPI). Similarly, some savings bonds and National Savings & Investments (NS&I) products have historically offered inflation-linked returns.
These products aren’t always the highest-returning option, but they offer a degree of protection that standard fixed-rate products don’t.
3. Invest in Real Assets and Equities
Over the long term, equities (shares in companies) have historically provided returns that outpace inflation. Property, commodities, and infrastructure investments have also tended to hold or grow their real value over time, though they come with their own risks and complexities.
Stocks and shares ISAs, broadly diversified index funds, and pension contributions invested in growth assets are all ways that long-term savers can aim to grow wealth in real terms rather than just nominal ones. Of course, investments can fall in value as well as rise, and this approach suits those with a longer time horizon and tolerance for short-term volatility.
4. Diversify Across Asset Classes
No single asset class performs best in all economic environments. A diversified portfolio — spreading money across cash, equities, bonds, and potentially property — reduces the risk that any one source of return is devastated by a particular inflation scenario.
5. Review Your Financial Plan Regularly
Inflation rates change, interest rates change, and your own financial circumstances change. What was a sensible savings strategy three years ago may be inadequate today. Building in an annual or biannual review of where your money is held, what it’s earning, and how that compares to the current rate of inflation is a simple but powerful habit.
The Psychological Trap: Why We Ignore Inflation
One reason inflation is so damaging is that it’s psychologically invisible. Seeing your savings account balance increase from £15,000 to £15,600 over a year feels like progress — even if inflation was running at 5% and your real purchasing power has actually declined.
This is sometimes called money illusion — the tendency to think about financial values in nominal terms rather than real ones. Overcoming this illusion requires a shift in how you measure financial progress. Instead of asking “how much do I have?”, the more useful question becomes “what can this money actually buy, and how does that compare to last year?” Many people underestimate financial literacy precisely because these real-terms distinctions are rarely taught in straightforward terms.
When you start thinking in real terms, the urgency of finding inflation-beating returns becomes much clearer.
A Final Word on Keeping Your Savings Working
Inflation is not a problem that can be completely solved — it’s an inherent feature of modern economies. But being aware of its effects, understanding the gap between nominal and real returns, and taking deliberate steps to close that gap can make an enormous difference to your long-term financial wellbeing.
The savers who fare best aren’t necessarily those who earn the most or save the most — they’re the ones who pay attention to what their money is actually doing in real-world terms. By regularly reviewing savings rates, considering a broader range of financial products, and staying informed about the economic environment, it’s entirely possible to protect and even grow the real value of your money over time, even in periods of elevated inflation.
Inflation may be quiet, but with the right knowledge, its erosive effects don’t have to go unchecked.